United Rentals: A discounted entry point for infrastructure growth
The heavy equipment lessor trades at 17.3 times forward earnings while expanding faster than the S&P 500, prompting a bullish options strategy from analyst Mike Khouw.
By Ricardo Whitaker ·
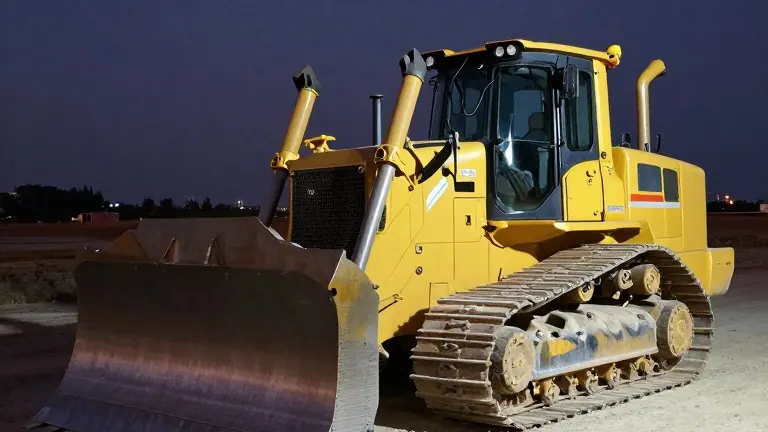
United Rentals (NYSE: URI) currently trades at a valuation that lags behind its growth metrics, creating a specific opportunity for investors focused on infrastructure spending. The equipment rental giant is compounding revenues and EBITDA at a rate that exceeds the cap-weighted S&P 500, yet its market price reflects a forward multiple that is lower than the broader market average.
The company has maintained this trajectory through recent quarters. In its most recent third-quarter report, URI delivered earnings that exceeded expectations. Management subsequently raised its forward guidance. This performance triggered a wave of upward revisions in sell-side estimates, a factor that historically correlates with short-term stock outperformance.
The valuation gap is evident in specific financial metrics. The stock trades at approximately 17.3 times forward earnings estimates of $61.10 per share. On an enterprise value basis, it sits at 8.8 times projected fiscal year 2027 EBITDA of $9.25 billion. These figures are lower than what investors typically pay for a company with similar growth characteristics in the current market.
Demand for the company's services is driven by a recovering nonresidential construction sector. Rental rates have remained resilient despite the sector's volatility. While a potential slowdown in data center construction presents a future risk, broader infrastructure demand supports the current business model. The company's ability to deploy heavy equipment to remote sites provides a competitive advantage in this environment.
Analyst Mike Khouw notes that the stock is not cheap relative to its own history. It trades roughly 20% to 25% above its five-year average multiple. This premium reflects the company's scale and capital efficiency, but it also introduces the risk of mean reversion. If the multiple compresses back to historical levels, the stock could face downside pressure.
To address this valuation tension, Khouw proposes a defined-risk options trade. Instead of buying shares outright at the current premium, he suggests selling cash-covered puts. The implied volatility for URI options is currently in the 42% to 45% range, offering a substantial premium for this strategy. This approach allows an investor to collect income while setting a specific entry price for the stock.
The mechanics of this trade offer two distinct outcomes. If the stock price rises or remains stable, the puts expire worthless and the investor keeps the premium. If the stock price falls to the strike price, the investor acquires the shares at a lower effective cost basis. This entry point can be further reduced by writing covered calls against the acquired position.
Tidal, the firm associated with Khouw, holds all securities mentioned in the analysis. The strategy relies on the stock's momentum and fundamental strength while hedging against the risk of its elevated historical valuation. The trade capitalizes on the company's role in heavy infrastructure work, leveraging the current market's willingness to pay a premium for volatility protection.
More Business · Watch Your Wallet · Report a business · Got a Story?